Bank of America Unlimited gets searched a lot because the value proposition stays simple: flat-rate cash back, no annual fee, and a promo APR window that can help with timing. Approval and cost still hinge on credit profile, payment habits, and how the fee terms hit real spending, especially outside the U.S.
A clean way to evaluate this card starts with three questions. Credit readiness comes first, since the underwriting target leans toward established borrowers.
Fee exposure comes next, since transfers, cash advances, and overseas use can add cost fast. Rewards math comes last, because a flat rate only shines when the card stays cheap to carry.
Bank Of America Unlimited At A Glance
A predictable rewards card works best when the basics stay tight. Bank of America markets this card around an introductory earn rate that steps down after year one, paired with a long intro APR period on purchases and eligible transfers.
The headline structure looks like this: 2% cash back on purchases during the first year from account opening, then 1.5% cash back on purchases going forward. Cash rewards generally stay available as long as the account remains open, which matters for people who redeem less frequently.
Intro APR Terms Also Drive Interest
A 0% intro APR applies for a set promotional window on purchases, plus on balance transfers made early in the account lifecycle. Once the intro offer ends, pricing reverts to a variable range tied to creditworthiness and broader rate conditions.
Credit Score Standards and Approval Reality
Strong applications usually land in a band lenders label as a good to excellent credit score, commonly described as roughly 670 to 850. That range does not guarantee approval, yet it frames the risk tier the issuer tends to prefer for an unsecured rewards card.
Score alone is rarely the whole story. Issuers weigh income stability, existing debt load, prior late payments, and the depth of credit history. Thin files sometimes struggle even with a decent score, since the model has fewer signals to rely on.
Approval chatter often mentions averages, yet averages can mislead. Some approvals happen around the low 700s, while long-established profiles can sit far higher. A practical approach centers on fundamentals that underwriters like: low utilization, on-time payment history, and manageable monthly obligations relative to reported income.
Fees and Interest Terms That Matter Most
Fee terms decide whether a “simple cash back” card stays simple. Several costs show up only in certain situations, so the focus should stay on the scenarios that match actual habits.
Key cost points usually include the following:
- Annual fee stays at $0, which keeps holding cost low.
- balance transfer fee can start at 3% for transfers made in the early window, then move to 5% afterward.
- foreign transaction fee is commonly 3%, which can erase rewards on overseas purchases or foreign-currency online shopping.
- cash advance fee is often 5% of the advance, plus interest that starts immediately.
Variable APR applies after the promo window, with recent published ranges commonly shown around 17.49% to 27.49%, depending on creditworthiness.
Balance transfer mechanics need extra attention. Transfers typically must be made within the first 60 days to qualify for the intro fee and the promo APR window, and transfers usually cannot be used to pay another Bank of America account.
Payment allocation rules also matter: minimum payments generally go to lower-interest balances first, while additional payments go toward higher-interest balances.
Rewards Structure and Preferred Rewards Upside
Flat-rate cards win on low mental load. Every eligible purchase earns the same base rate, so category tracking rarely becomes a weekly chore. That said, the year-one earn rate and the relationship program can change the math enough to matter.
Base Earning and First-Year Boost
An early earning bump pushes the card above many 1.5% competitors for the first year, assuming spending stays consistent. After the promo year, the card returns to its ongoing unlimited 1.5% rate, which competes best when fees remain low and interest gets avoided.
Sign-up offers also show up frequently, commonly framed as a $200 online cash rewards bonus after hitting a spending threshold in the first 90 days. Offer terms can vary over time, so the safest move involves checking the current disclosure page right before applying.
Relationship Bonuses Through Preferred Rewards
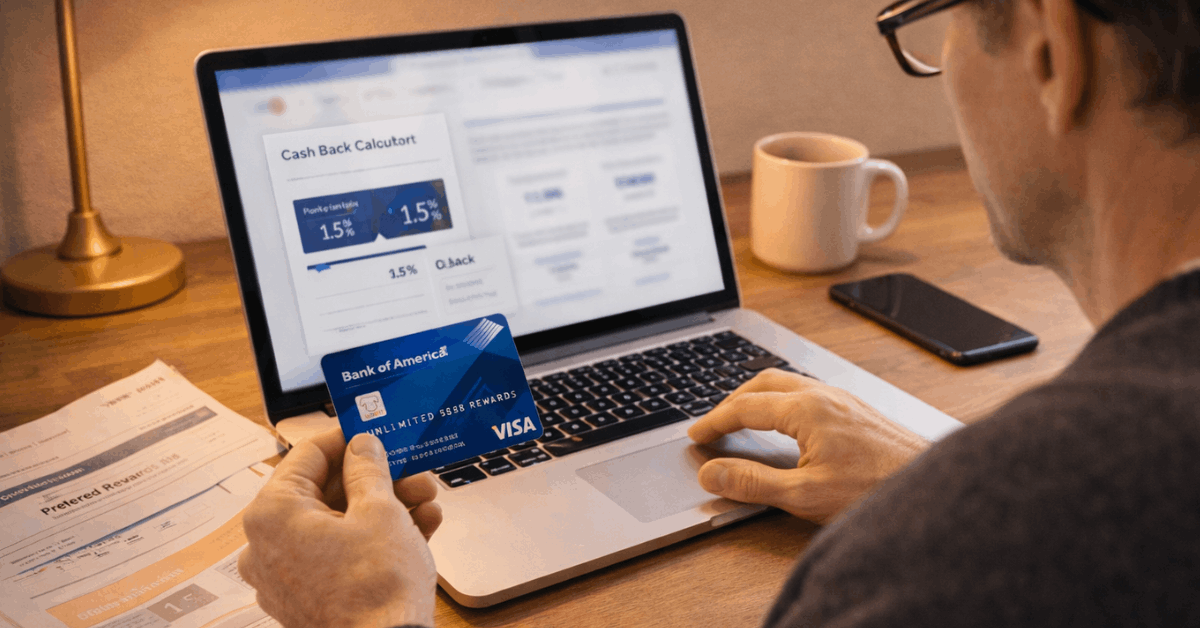
Bank of America’s relationship program can add meaningful upside for customers who qualify. The Preferred Rewards bonus is typically published as a 25% to 75% boost on eligible credit card rewards, depending on tier. Higher tiers usually require larger qualifying balances across Bank of America deposit accounts and Merrill investment accounts.
Rate boosts sound small until the annual spend is decent. A 1.5% base rate increased by 25% becomes 1.875%, while a 75% boost pushes the effective earn rate to 2.625%. That difference can outweigh many competing cash-back offers, but only for people already holding those qualifying balances.
Secured Version For Building Or Rebuilding Credit
A secured option exists for people who need a more accessible entry point. Security deposits reduce risk for the issuer, which often makes approval more achievable when credit history is limited or damaged.
Secured Credit Card Deposit
The secured credit card deposit requirement typically starts at $200, with published maximum deposits commonly shown up to $5,000. The deposit often becomes the baseline for the credit limit, though income and ability-to-pay factors can still influence the final line.
Secured cards often differ from unsecured cards in two important ways. Intro APR offers usually do not apply, and new account bonuses may not be available. A secured product can still help build payment history, since responsible use and on-time payments are the primary drivers of long-term score recovery.
Periodic reviews sometimes allow a path toward getting the deposit back, though outcomes depend on overall credit history and account management. No guarantee exists, so expectations should stay realistic.
Safety Tools and Everyday Account Controls
Security and control features can matter as much as rewards, especially for people managing multiple payment dates and travel-related spend. Bank of America highlights a combination of monitoring, alerts, and digital payment options.
Common tools and protections include:
- Fraud monitoring that flags unusual patterns, plus a $0 Liability Guarantee for unauthorized transactions, subject to claim requirements.
- Account alerts that can notify about due dates, posted payments, and balance changes, usually by email or text.
- Digital wallet compatibility for mobile pay options such as Apple Pay, Google Pay, and Samsung Pay.
Optional overdraft support through Balance Connect when linked to an eligible Bank of America checking account, treated as a cash advance under the card agreement, and accruing interest from the transaction date.
Overdraft features deserve careful handling. Credit-card-backed overdraft protection can prevent declines, yet it can also create expensive cash-advance-style interest if used frequently. A cleaner strategy involves alerts and buffer cash, then overdraft tools only as a last-resort backstop.
Last Thoughts
Bank of America Unlimited can serve as a low-friction cash-back card when the account stays “clean” in real life. Flat rewards, a $0 annual fee, and a promo APR window look strong on paper, yet the real decision comes down to fee exposure and repayment discipline.
Foreign transaction fees, cash-advance pricing, and post-intro APR can erase the simplicity fast if balances linger or spending shifts overseas.
Kept inside its best lane, though, it’s a straightforward pick for established credit profiles that want predictable earnings, plus meaningful upside for people already positioned to qualify for Preferred Rewards.
Disclaimer
This site provides general information on credit cards and payment products, not financial, legal, or tax advice; always verify rates, fees, and terms with the issuing bank before applying.